Behavioral credit risk, built for lenders

Credit should see the person, not just the past.

ConfirmU gives lenders a validated behavioral risk signal for small business owners and consumers with limited credit history, from a three minute game that needs no bureau file.

Applicant with no bureau file

No credit history
Bureau record: silent

Returned to the lender

712Band B

Illustrative output shown to explain the flow. Not a published ConfirmU statistic.

Our mission

Financial inclusion for three billion people.

Credit risk assessment depends on historic payment information, so a consumer cannot access credit unless they have had credit before.

There are three billion consumers worldwide that cannot access the financial services they need. We believe this is wrong, and that everyone should be able to access the products and services they need regardless of age, location or past performance.

Consumers without access to credit
3BConsumers without access to credit
To complete a behavioral assessment
3 minTo complete a behavioral assessment
Bureau records required
0Bureau records required

Partners

  • Experian logoExperianGlobal credit bureau partnership
  • Bridge2Capital logoBridge2CapitalIntegrated into underwriting
  • MyFugo logoMyFugoCredit risk scoring partnership

How it works

Play, signal, score, decision.

ConfirmU supplements your existing underwriting process. It does not replace it. The behavioral score works alongside bureau data, bank statements, and the other signals you already use.

  1. 01

    Embed the game

    A three minute behavioral assessment sits inside your application flow. Borrowers play on any device, at their own pace.

    SDK and API integration into your existing digital onboarding journey.

  2. 02

    Capture behavioral signals

    As the borrower plays, ConfirmU measures psychometric and behavioral traits in real time. There is no self reporting and no gaming the answers.

    Game telemetry captures behavioral data points throughout the session.

  3. 03

    Receive a risk score

    Signals are processed through a validated model and returned to your underwriting system as a single, interpretable risk score.

    Score returned via API once the game is complete.

Where the sequence lands

Decision support, inside the workflow the credit team already uses.

ConfirmU is designed to supplement, not replace, your existing underwriting processes. The lender keeps full decision authority.

Bureau dataBank dataBehavioral signalDecision

Business value

Find qualified borrowers hidden by traditional scoring.

One assessment framework, configured per portfolio, that adds a signal where bureau data runs out.

The lift

More of the pool becomes reviewable.

Applicants who cannot be placed in a risk band on bureau data alone can be placed once a behavioral signal is added, so credit teams can review cases they previously had to set aside.

Assessment length
3 min
Bureau file required
None

Reviewable applicants by risk band

Very lowLowMediumHighVery high
Bureau data aloneWith behavioral signal

Illustrative shape of a lender portfolio, shown to explain the effect of an additional signal. Not a published ConfirmU statistic.

  • 01

    Assess applicants with limited credit history

    Evaluate consumers and small business owners who lack traditional credit history, without turning them away.

  • 02

    Add behavioral insight

    Layer psychometric signals on top of your existing data to surface willingness to repay that numbers alone miss.

  • 03

    Support consumer and SME lending

    One assessment framework works across personal loans and small business credit, configured per portfolio.

  • 04

    Configure for local markets

    Adapt assessments to language, culture, and regulatory context so scores stay relevant in every market you operate.

The assessment

Try a three minute assessment, live.

A four question preview of the ConfirmU assessment. Your answers build a behavioral signal in real time. Nothing is stored or sent. This is a demonstration only.

Assessment progress0%

Ready to begin?

Four questions. About three minutes.

You will face short scenarios about budgeting, prioritizing tasks, and making tradeoffs. There are no right answers. Your pattern of choices is what matters.

Behavioral signals measured

Each signal captures a different dimension of behavior.

Planning

How applicants sequence tasks and anticipate future steps.

Organization

How applicants structure resources and manage competing priorities.

Financial conscientiousness

Care and consistency in resource allocation decisions.

Decision consistency

Stability of choices under varying time pressure.

The evidence

What a behavioral signal shows that a bureau cannot.

Validated against real payment performance, then read back through four lenses on the same pool of applicants with limited credit history.

0%+

Correlation for selected psychometric traits related to financial conscientiousness

0%+

Positive correlation for behavioral traits including planning and organizational skills

0%

Of assessed applicants with limited credit history fell within lender risk appetite

0%+

Correlation where a bureau score already existed

Results reflect ConfirmU testing and client deployments. Outcomes vary by portfolio, market, and implementation.

Approval lift

Applicants with limited credit history now reviewable

0%
+38 pt lift
Bureau alone24%

Score distribution shift

Bands applicants with limited credit history fall into

Bureau data aloneWith behavioral signal

Default rate trend

Over the first 10 months of a portfolio

Default rate at month 102.1% 4.3%

Trait profile

Behavioral dimensions measured

PlanningOrganizationConscientiousnessConsistencyFocus
BureauSignal

Charts are illustrative representations of the kind of lift lenders can observe when a behavioral signal is layered on top of bureau data. They are not published ConfirmU statistics and do not represent any specific lender's portfolio.

Use cases

Built for both sides of the lending book.

One behavioral assessment framework, applied to two distinct lending contexts and configured per portfolio.

Limited credit history

Traditional recordDecision support
Illustrative view of where the behavioral signal enters the decision. Not a published ConfirmU statistic.
01

Consumer lending

The problem
Millions of creditworthy consumers are rejected because they have no credit history: recent movers, young professionals, first time borrowers.
ConfirmU's role
ConfirmU adds a behavioral risk score from a three minute game, giving lenders a signal where bureau data is silent.
Lender outcome
Lenders can identify applicants with limited credit history who fall within their risk appetite, expanding approval rates without increasing exposure.
Small business owner

Traditional recordDecision support
Illustrative view of where the behavioral signal enters the decision. Not a published ConfirmU statistic.
02

SME lending

The problem
Small business owners often lack the financial documentation and credit footprint that traditional SME underwriting requires.
ConfirmU's role
ConfirmU assesses the owner’s behavioral traits (planning, organization, financial conscientiousness) as a proxy for repayment intent.
Lender outcome
Lenders gain an additional signal for SME risk assessment, supporting decisions where financial statements alone are insufficient.

These use cases describe how ConfirmU supports lending decisions. They do not guarantee approval outcomes, which remain the lender's responsibility.

Privacy and responsible use

Built around consent and responsible use.

No certifications are claimed unless verified by ConfirmU. The principles below describe how behavioral data is collected, processed, and used.

  1. 01

    Consent based data

    Borrowers explicitly consent before playing. No data is collected without informed, opt in agreement.

  2. 02

    Responsible data handling

    Behavioral signals are processed securely and used solely for credit risk assessment. Data is not sold or shared with third parties.

  3. 03

    Model validation

    ConfirmU models are validated against real payment performance data and monitored for bias and drift over time.

  4. 04

    Responsible use

    ConfirmU scores are designed to supplement human underwriting decisions, not replace them. Lenders retain full decision authority.

The consent chain

Consent is captured before anything is measured. Only then does a behavioral signal exist, and only the signal reaches the lender.

  1. Interaction

    Borrower plays the assessment

  2. Permission

    Explicit, informed consent

  3. Processing

    Secure, purpose limited

  4. Behavioral output

    One interpretable score

  5. Lender delivery

    Returned through your API

Privacy policy: not yet published. A detailed privacy policy is pending verification by ConfirmU and is not available at this address. It will be linked here once supplied.

What partners say about ConfirmU

In their words

“We have found that customers onboarded using the psychometric test have not defaulted during the Covid period. This has reaffirmed our belief in ConfirmU. We are making their service an integral part of our underwriting process.”

Bridge2Capital

Partner

About ConfirmU

A mission to democratize lending.

ConfirmU was founded after a colleague (an intelligent professional in a secure job) was denied a personal loan simply because he had moved country and left his credit history behind.

By measuring behavioral and psychometric traits through a short game, ConfirmU gives lenders a risk signal that works regardless of age, location, or credit history, enabling financial inclusion one assessment at a time.

Our team

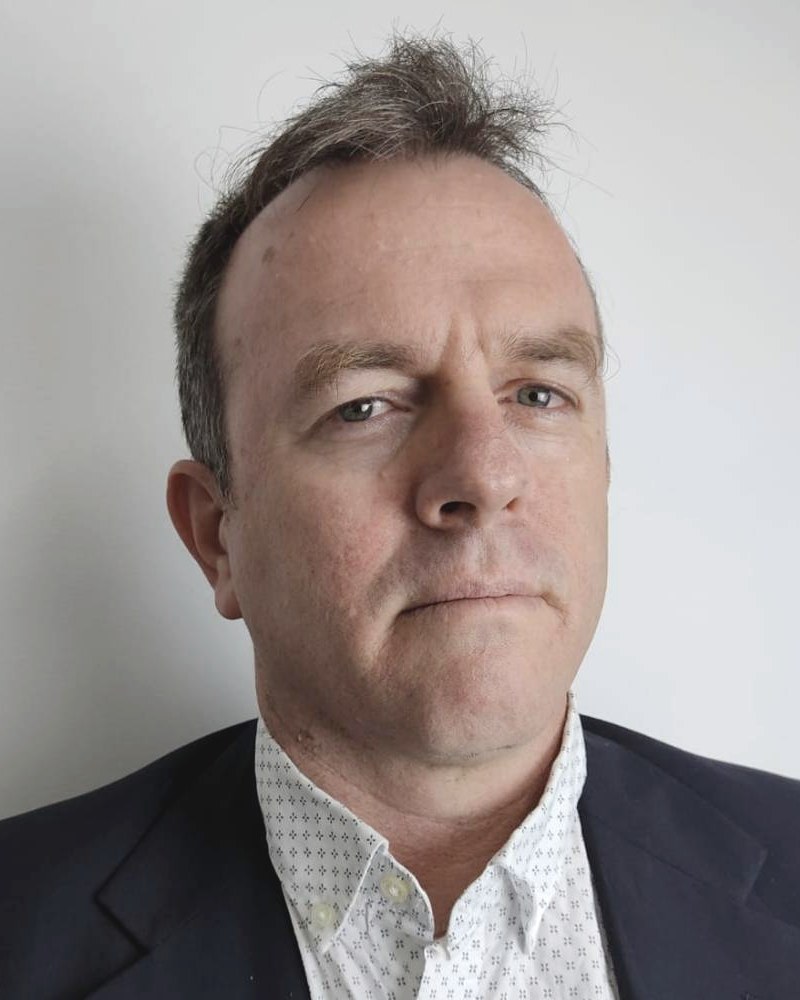
  • Portrait of Yatir Zaluski, Cofounder & CEO

    Yatir Zaluski

    Cofounder & CEO

    Enterprise software veteran, fintech entrepreneur, digitisation leader, certified accountant.

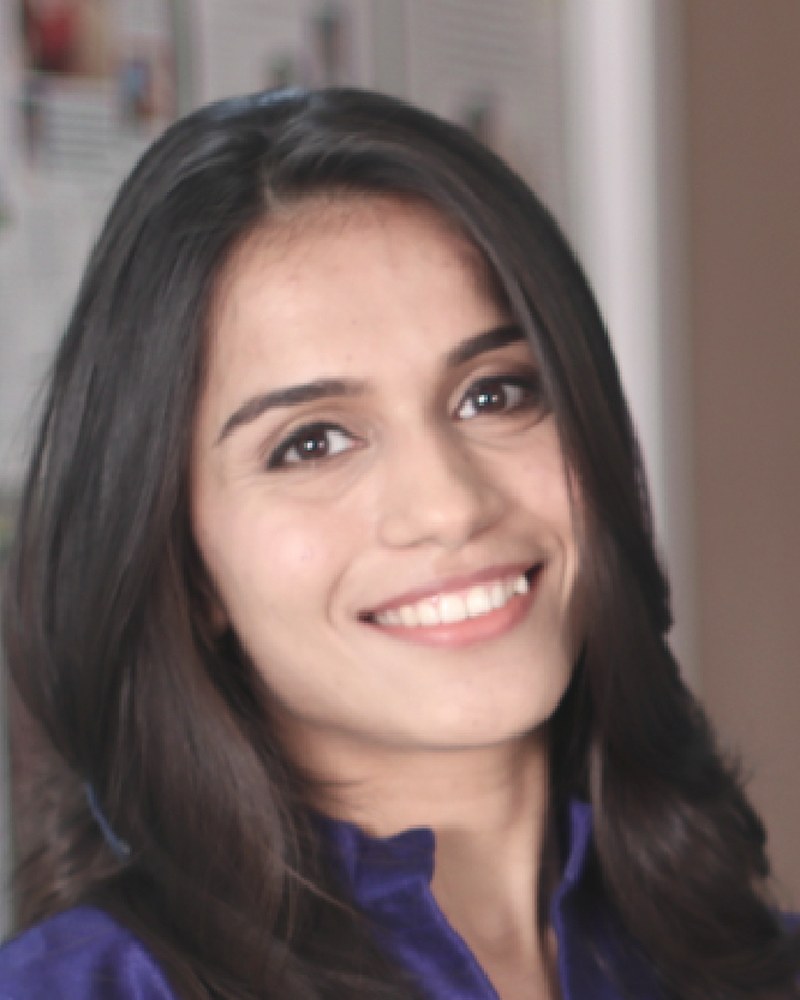
  • Portrait of Namrata Jain, Lead Psychologist & Game Designer

    Namrata Jain

    Lead Psychologist & Game Designer

    Internationally recognised psychologist and mental health practitioner, entrepreneur, TEDx speaker. MA Applied Psychology, University of Mumbai.

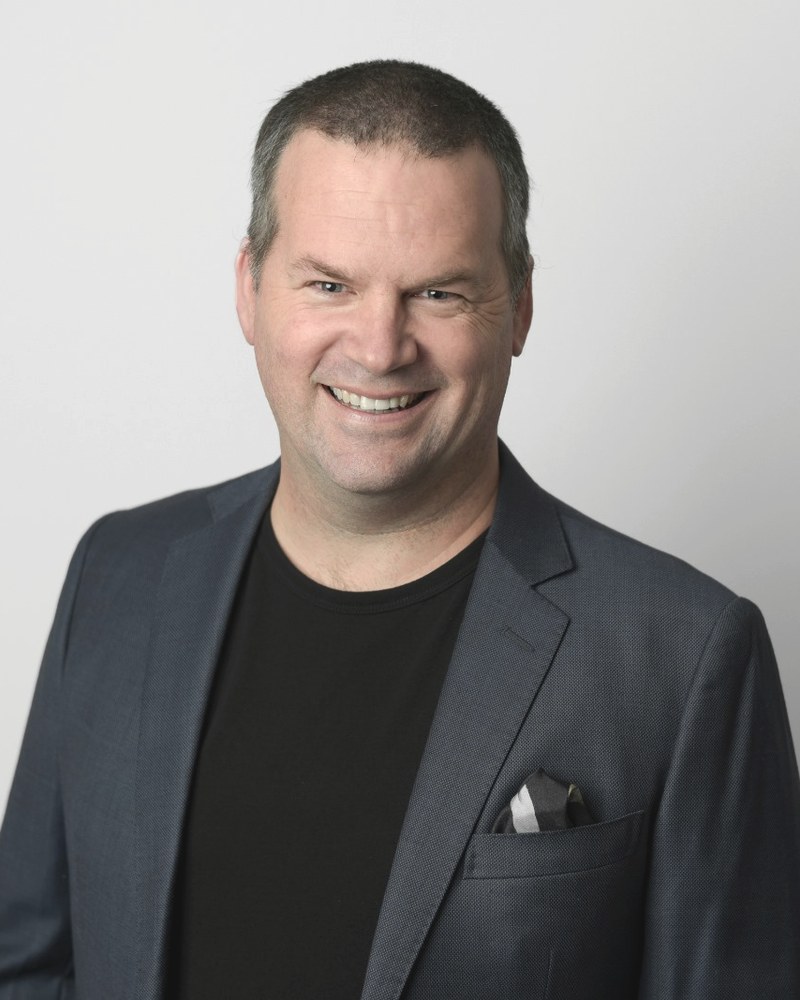
  • Portrait of Brendan Le Grange, Chief Solution Architect

    Brendan Le Grange

    Chief Solution Architect

    Passionate for credit risk modeling and owner of the Lending to Strangers podcast series.

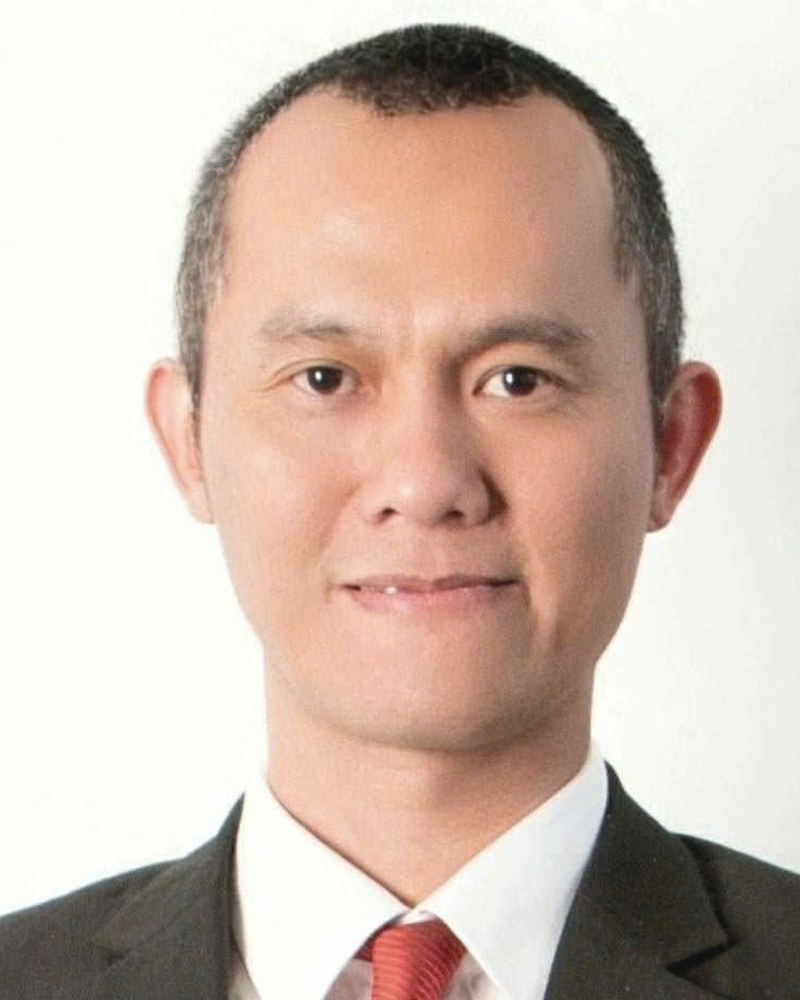
  • Portrait of Phu Nguyen, APAC Director

    Phu Nguyen

    APAC Director

    Business builder with 25+ years across consumer finance, digital banking, and credit technology in Vietnam, Cambodia, Thailand, and China. Built and launched Liobank.

Portrait of Yatir Zaluski, Cofounder & CEO, ConfirmU

Yatir Zaluski

Cofounder & CEO, ConfirmU

A note from our CEO

The global credit system is broken for billions of people.

Traditional credit scoring depends on historic payment data. If you have never had credit, you cannot get credit. It is a catch 22 that locks out young professionals, recent movers, small business owners, and entire emerging markets.

ConfirmU breaks that cycle. Our three minute behavioral game reveals psychometric traits (planning, organization, financial conscientiousness) that correlate with repayment behavior. We give lenders a signal where bureaus are silent, and we give creditworthy people a chance to be seen.

Financial inclusion is not charity. It is good business. When lenders can safely say yes to more people, everyone wins.

Media and blog

Stories, media, and ideas.

Coverage, talks, and writing from the ConfirmU team on behavioral credit and financial inclusion.

Featured film

Why ConfirmU exists: the people a bureau file cannot describe, and what behavior reveals about them.

More from ConfirmU

Contact

Request a demonstration.

Tell us about your lending portfolio and we'll show you how ConfirmU's behavioral assessment fits into your underwriting flow.

  • See a live assessment and a sample risk score.
  • Discuss integration with your existing underwriting system.
  • Review validation data for your market and portfolio.

Demo form. This form is a front end demonstration. Submissions are not transmitted or stored until a backend service is connected.

Fields marked with an asterisk are required.